Why Rent Keeps Outrunning Wages
The mechanics behind decades of housing costs rising faster than incomes, from zoning and construction productivity to institutional landlords, and what actually shifts the number.
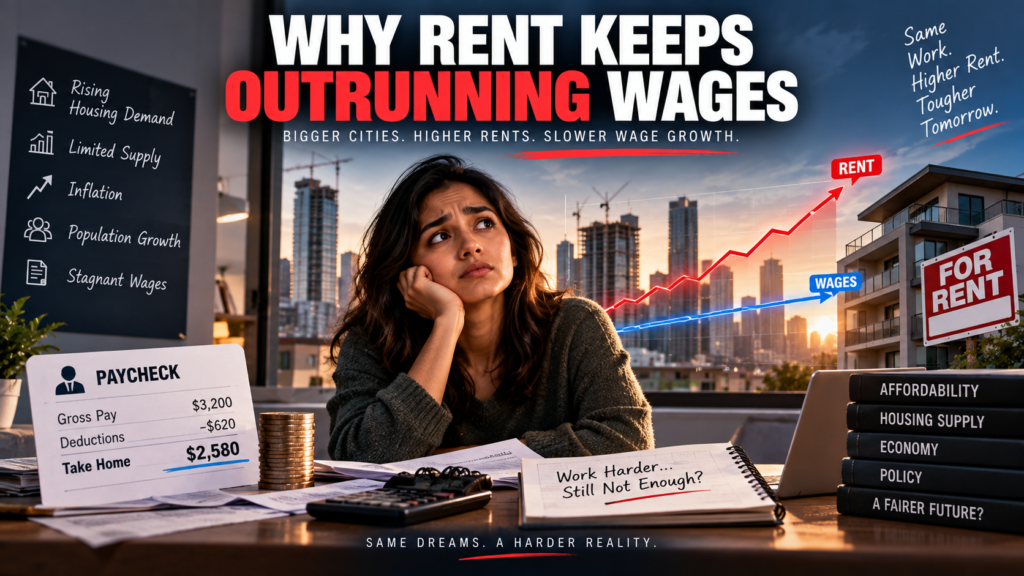
Ask someone who moved to a city ten years ago what they paid for their first apartment there. Watch their face while they say the number out loud. Then watch them do the mental math on what the same unit lists for now, and compare it to what their salary did over the same decade. That gap, the one that makes people laugh in a slightly stunned way, is the whole subject. That gap is the short answer to why rent keeps rising faster than the paycheck that has to cover it.
Rent outpacing wages is not a recent surprise. In most wealthy countries, housing costs have grown faster than median earnings across multiple decades, with pauses during recessions and sharp catch-up periods afterward. The share of renters spending more than thirty percent of income on housing, the traditional threshold for being cost burdened, has trended upward for a long time in national housing data, and the share spending more than half has grown too.
The interesting question is not whether this is happening. It is why the mechanism keeps producing the same result even when politicians of every stripe promise to fix it.
Housing Supply Responds Slowly, and Sometimes Not At All
Most goods respond to rising prices by appearing in greater quantity. Housing is unusually bad at this.
A new apartment building takes years from land assembly to occupancy. Rezoning, environmental review, design approval, community meetings, permits, financing, then construction itself. By the time units arrive, the conditions that justified building them may have changed completely. Developers who started projects during a boom often deliver into a slump, which teaches a lesson they remember during the next boom.
Then there is what gets built. In many expensive cities, land costs and approval risk are high enough that only luxury units pencil out financially. Building a modest apartment on land that expensive, under a process that slow, loses money. So supply arrives at the top of the market, which helps eventually through people moving up and freeing older units, but slowly and invisibly to anyone hunting for something affordable this month.
Zoning does much of the work here. Enormous portions of residential land in North American and Australian cities are restricted to detached single-family houses. Height limits, minimum lot sizes, parking requirements and setback rules cap how many homes can exist on land where demand is highest. When a city cannot add homes near jobs, the demand does not evaporate. It bids up what already exists.
The Construction Cost Problem Nobody Solved
Building has grown more expensive in real terms across most developed economies. Materials, skilled labor shortages after older tradespeople retired, tighter building codes, energy standards, and financing costs all push the same direction.
Construction is also one of the few major industries where productivity has been roughly flat for decades while manufacturing and agriculture transformed. A house is still assembled largely by hand, on site, in weather, by many separate trades coordinated imperfectly. Prefabrication and modular building keep being promised as the answer and keep running into transport costs, local code differences and financing that is unfamiliar with the model.
Higher interest rates make this worse in a way that is easy to miss. Rate rises hit development financing directly, so fewer projects start, meaning less supply arrives two or three years later, exactly when the previous pipeline runs dry. Meanwhile higher rates also lock existing homeowners into cheap mortgages they will not give up, which chokes off the resale market and pushes more people into renting. Demand rises and supply falls at the same time.
Wages Are Not Rising The Way Rent Is
The other half of the ratio gets less attention. In most rich countries, median real wage growth has been modest for a long stretch, and the gains that did occur concentrated heavily among higher earners.
This matters more than the averages suggest, because rents in a given neighborhood are set at the margin by whoever is willing and able to pay most. If the top quarter of earners in a city sees strong income growth while the middle sees very little, rents track the top quarter. Everyone else absorbs the difference by spending a larger share of a flatter income, moving further out, or living with more people.
Remote work sharpened this. When higher earners could keep metropolitan salaries while living in smaller cities and towns, local rents in those places moved toward what the newcomers could pay rather than what local wages supported. Plenty of mid-sized towns saw the steepest rent increases in their history over a short period for exactly this reason.
Renting Became An Asset Class
Institutional ownership of rental housing has grown considerably, particularly in single-family rentals and larger apartment portfolios. The share is still a minority of the total market in most countries, but it is concentrated in specific metros and specific price tiers, which is where its effect shows.
The behavioral difference matters. A small landlord with three units often keeps a good tenant at a below-market rent because turnover is a hassle and they know the person. A portfolio managed against quarterly return targets prices units to the market, uses revenue management software, and treats vacancy as a calculation rather than a worry. Neither is villainous. They simply produce different rent trajectories, and the second one produces faster increases.
Short-term rental platforms pulled units out of long-term stock too. The effect varies wildly by city, negligible in some and significant in tourist-heavy neighborhoods where a meaningful share of housing shifted to nightly rental. Many cities have since restricted this, with mixed results.
Why Rent Control Does Not Settle It
Housing economists disagree about many things and mostly agree about this: rent stabilization protects the people who currently hold covered units and tends to reduce the supply and quality of rental housing over time. Landlords convert units to condos, take them off the market, or defer maintenance. New arrivals face a smaller, more expensive uncontrolled market.
That does not make it useless. Preventing sudden displacement of long-term residents has real social value that a pure supply analysis ignores, and cheap stability for existing tenants is worth something. But it redistributes scarcity rather than reducing it. A city that controls rents without adding homes gets a lucky protected group and a punishing market for everyone else.
Why Rent Keeps Rising, And What Actually Moves The Number
Places that have made progress usually did several unglamorous things at once.
- Legalized more homes where people want to live. Allowing duplexes and small apartment buildings in areas previously restricted to detached houses, raising height limits near transit, and permitting accessory units in backyards and garages. Boring, incremental, and the closest thing to a consensus fix among researchers.
- Made approval predictable. Not necessarily easier, but faster and rule-based, so a project meeting the written standards gets approved without years of discretionary review. Uncertainty is itself a cost that gets priced into rent.
- Built subsidized housing directly. Market supply alone does not reach the lowest income tiers, because the cost of building anything exceeds what those households can pay. Countries with large social or nonprofit housing sectors show notably different cost-burden patterns.
- Improved transit. A neighborhood twenty minutes from jobs by reliable train is functionally part of the expensive housing market. Transit expands the supply of viable locations without a single new building permit.
None of these work quickly. All of them require sustained political will against neighbors who prefer things as they are, which is why they so rarely happen at scale.
What This Means For The Person Signing A Lease
Structural analysis does not pay your rent, so a few practical things follow from all this.
Renewal is usually cheaper than moving, and landlords know turnover costs them real money in vacancy, cleaning and listing. Asking for a smaller increase in exchange for a longer lease is a normal negotiation, and it works more often than people expect because it addresses the landlord’s actual risk.
Watch what is under construction near you. A large building delivering units in your area often softens rents locally for a while, and the best time to negotiate or move is when a new building is filling up and offering concessions.
Understand your local rules before you need them. Notice periods for increases, deposit limits, repair obligations and eviction protections vary enormously by city and country, and tenants routinely accept things they could have refused simply because nobody told them the rule existed.
And treat the thirty percent guideline as a rough historical benchmark rather than a law of nature. In genuinely expensive cities it has been unreachable for ordinary earners for years. What matters more is what remains after housing: whether you can save anything, absorb a surprise expense, and leave a bad situation. A household at thirty-five percent with savings is in better shape than one at twenty-eight percent with none. The ratio was always a proxy for that question, and the question is the one worth answering.
Related reading
More on the cost of having somewhere to live: